AssessmentEligibility against MISA’s conditions
Group presence, the activities the RHQ will actually run, and whether 15 roles can be filled in a year.
Company setup · Regional headquarters
An RHQ licence lets a multinational run its Middle East and North Africa business from Riyadh and pay 0% income tax on qualifying RHQ income for a renewable 30 years. It also starts two clocks: six months to begin the mandatory activities and twelve to have 15 people in post. We plan both before you apply.
Written by the formation desk at Saudia Company Formation, Lahore. Obligations taken from MISA’s Investor Guide (13th edition, 2026); tax terms from ZATCA’s Guideline for Regional Headquarters (May 2026). Checked 15 October 2026.
Definition
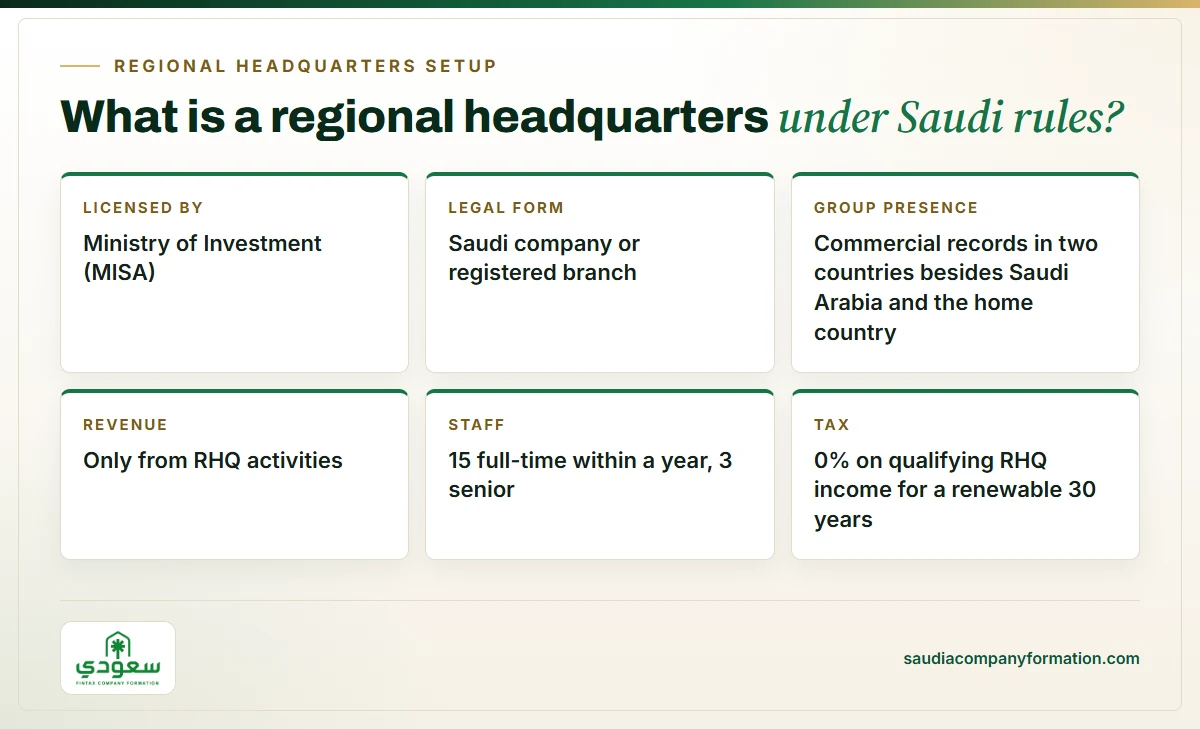
A regional headquarters (RHQ) is a Saudi entity licensed by MISA to support, manage and strategically direct a multinational group’s branches and subsidiaries across the Middle East and North Africa. It is set up as a Saudi company or as a registered branch of a foreign company, and the licence is a special category of MISA investment registration.
The catch is in what it may not do. Apart from its RHQ activities, an RHQ may not earn revenue, so the group’s Saudi sales almost always sit in a separate operating company. Of the set-up routes in our Saudi company formation services, this is the only one built for a whole group rather than a single business.
Month by month
An RHQ licence starts MISA’s clocks on the day it is issued: the mandatory activities must run by month 6, and 15 full-time staff and three optional activities must be in place by month 12. This is the plan we build backwards from those dates.
The roles for the 15 posts are named, with the three senior hires identified, because recruiting starts before the licence.
MISA issues the RHQ registration with the optional activities you chose, and its fee for the whole registration period is due within 30 days of notice. The CR, National Address and ZATCA registration follow.
Office leased (ZATCA’s substance rules require a physical office in the Kingdom), GOSI and Qiwa opened, visas filed for staff transferring from the group.
The mandatory RHQ activities must have started within six months of the licence.
At least three optional RHQ activities start; hiring continues toward 15.
At least 15 full-time employees on RHQ work, three at executive director or vice-president level.
Tax or zakat return within 120 days of year end, the annual economic substance report to ZATCA that the incentives depend on, CR confirmation and the MISA update.
Missing a substance condition has a set sequence under ZATCA’s RHQ tax rules: a 90-day notice to correct it, then fines that rise if the breach continues or repeats, then possible suspension of the tax incentives.
Our part
For a regional headquarters, we handle the eligibility check, the group documents, the MISA licence and CR, and a dated calendar for the first year. Tax opinions come from your group’s tax advisers, working from the structure we set up.
AssessmentGroup presence, the activities the RHQ will actually run, and whether 15 roles can be filled in a year.
Several countriesCommercial records and parent papers legalised in each country at the same time, not one after another.
MISA and CommerceThe RHQ registration with the optional activities chosen, then the CR, National Address and ZATCA.
Year oneEvery six- and twelve-month obligation diarised, with owners named on your side and ours.
How to start
An RHQ eligibility review is the first step for most groups, because it answers the two things a board asks first: does the group qualify, and can it fill 15 full-time roles within a year of the licence.
Assessment
A written view on eligibility, the activities, the staffing plan and the timeline, ready for a board paper.
For groups deciding whether to commit.
Quote the reviewSetup
Review, documents, licence, CR, ZATCA and the first-year calendar run to completion.
For groups that have decided to move.
Quote the setupLegal core
MISA registration and the CR, for groups whose HR and tax teams take it from there.
For groups with in-house Saudi teams.
Quote licensingEach option is quoted in writing as a fixed fee, with government and legalisation costs shown per country. How we work sets out what each stage covers.

Paperwork
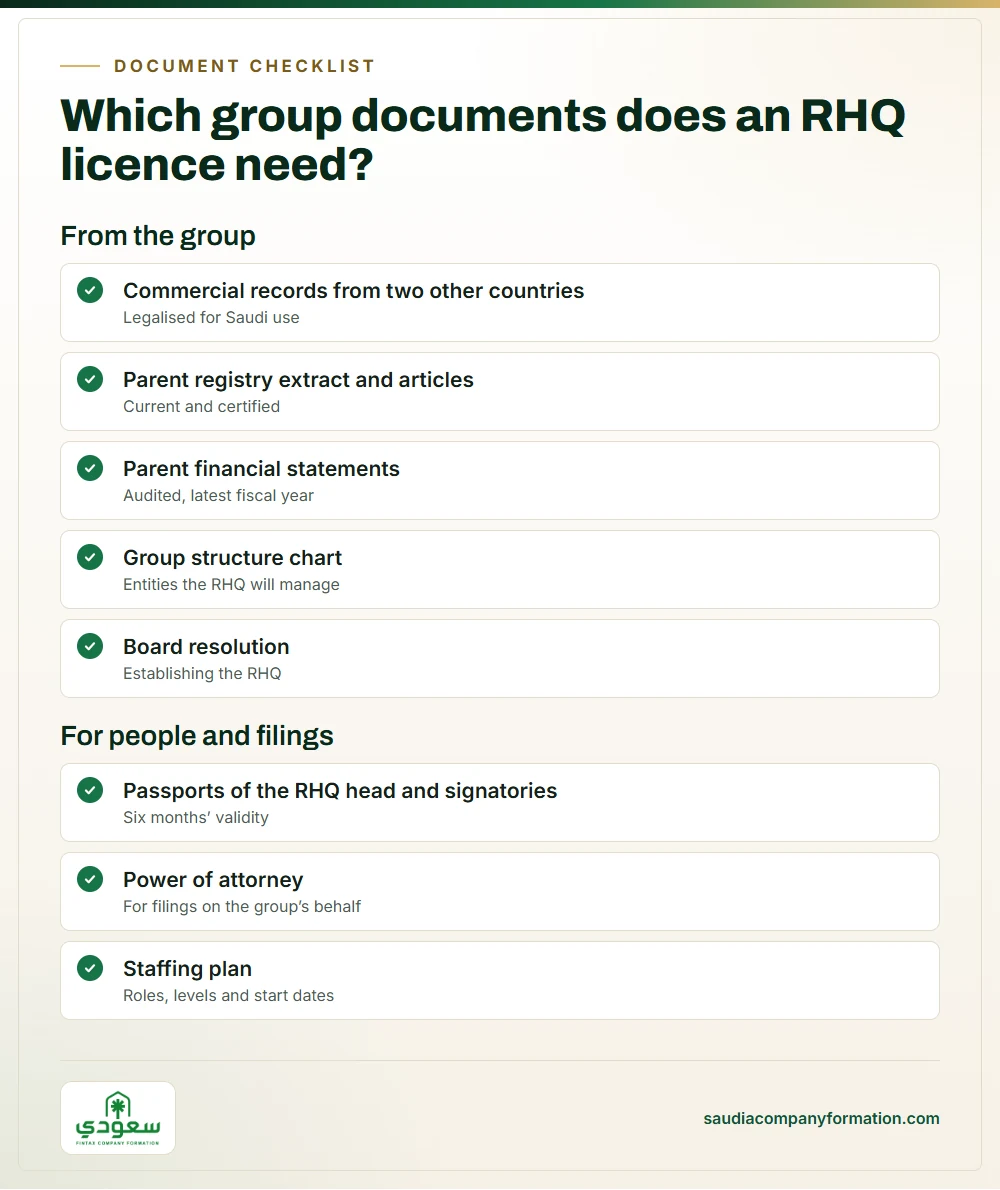
An RHQ licence file has to prove the group operates beyond Saudi Arabia: MISA asks for commercial records from two countries other than Saudi Arabia and the home country, alongside the parent’s own papers and its audited accounts. MISA’s guide still says “certified by the Saudi Embassy”, but since Saudi Arabia joined the Apostille Convention on 7 December 2022, records from member countries such as the UK, Germany or India take an apostille instead; records from the UAE, Qatar or Kuwait still need the embassy. We start the paperwork in every country at once, because these papers set the timeline.
Commercial records from two other countriesLegalised for Saudi use
Parent registry extract and articlesCurrent and certified
Parent financial statementsAudited, latest fiscal year
Group structure chartEntities the RHQ will manage
Board resolutionEstablishing the RHQ
Passports of the RHQ head and signatoriesSix months’ validity
Power of attorneyFor filings on the group’s behalf
Staffing planRoles, levels and start dates
Worth knowing
Three facts decide whether most groups go ahead with an RHQ: the government-contract rule in force since 1 January 2024, the 30-year tax package on qualifying income, and the ban on earning revenue outside RHQ activities.
Since 1 January 2024, Saudi government entities do not contract with multinational groups that have no regional headquarters in the Kingdom, apart from limited exceptions. Since November 2025 the government buyer applies for an exemption on the Etimad platform, before the tender or direct award starts.
For groups selling to the public sector, that rule turns the RHQ from an option into a precondition. An exemption is in the buyer’s hands, not yours, so plan as if it will not come. Giga-project buyers such as NEOM add their own supplier prequalification on top; our guide to winning NEOM business explains how that registration works.
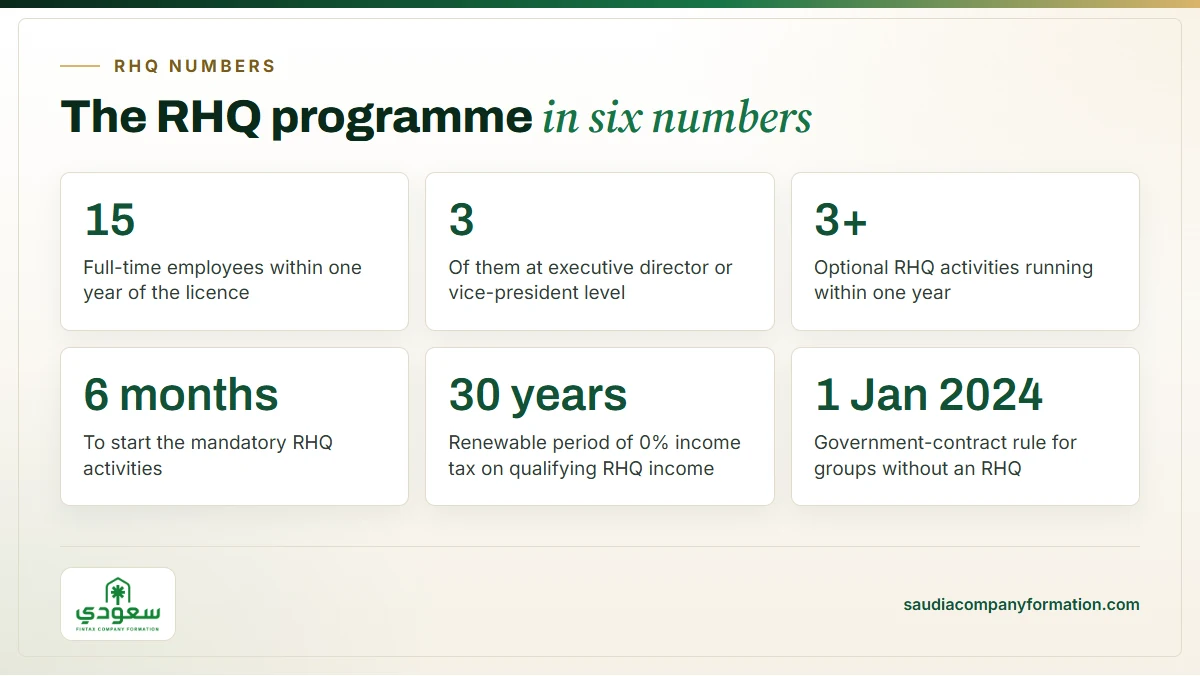
ZATCA’s RHQ tax rules (Board resolution 24-1-9 of 4 February 2024) give 0% income tax on eligible income from eligible RHQ activities for a renewable 30 years from the licence date. Withholding is 0% on dividends, on payments to related persons and on payments to unrelated persons for services the RHQ needs.
The catch is economic substance: a physical office in the Kingdom, board meetings held in Saudi Arabia, at least one resident director, real operating spend and enough qualified staff, confirmed in an annual report to ZATCA. Income from anything else is taxed normally, so keep the RHQ’s accounts cleanly apart from any operating company’s.

An RHQ may not directly carry on revenue-generating commercial operations beyond its RHQ activities, and MISA will not merge its registration with other investment records.
In practice that means two Saudi entities: the RHQ, and an LLC or branch that sells. We plan them together so their activities don’t overlap.
Side by side
A regional headquarters manages the group and an operating company sells, so the two entities answer to different rules on revenue, staffing, tax and government contracts.
Swipe to compare →
| Question | Regional headquarters | Operating LLC |
|---|---|---|
| Purpose | Manage the group’s MENA entities | Sell in Saudi Arabia |
| Revenue | RHQ activities only | Any registered activity |
| Staffing rule | 15 full-time within a year | Saudization by activity and size |
| Tax on profit | 0% on qualifying RHQ income | 20% on the foreign share |
| Government contracts | Satisfies the group requirement | Needs the group to have an RHQ |
The usual answer is both. The RHQ holds the regional management and the tax package; the LLC earns the Saudi revenue.
RHQ questions · 50
Based on MISA’s Investor Guide (13th edition, 2026) and ZATCA’s Guideline for Regional Headquarters (May 2026). Incentives are confirmed for your case by your tax advisers.
A regional headquarters directs a multinational group’s branches and subsidiaries in the Middle East and North Africa from Saudi Arabia. It runs the group’s regional management and functions such as finance, HR or legal support for those entities.
A Saudi company or a registered branch of a foreign company, holding an RHQ registration from MISA.
No. It may not earn revenue outside its RHQ activities. Saudi sales go through a separate operating entity.
Core management and strategic direction functions defined by MISA, which must start within six months of the licence.
Regional functions chosen at application from MISA’s list, such as finance, HR, marketing support, legal and training. At least three must start within a year.
No. MISA excludes RHQ registrations from merging with other investment records.
Most groups choose Riyadh for proximity to government and clients. Premises must suit the staff and functions.
Rarely. The programme assumes a multinational group able to staff 15 full-time roles.
A multinational group with commercial records in at least two countries besides Saudi Arabia and its home country, and the activities and people the programme requires.
MISA asks for records in two other countries. Because the RHQ manages MENA entities, groups usually point to regional subsidiaries.
Yes. The programme is open to multinational groups of any nationality that meet MISA’s conditions.
No, though many groups have one or form one alongside.
MISA’s RHQ category sets presence, activity and staffing conditions rather than a capital figure in its guide. Capital still has to fund the RHQ’s budget.
Often yes, provided the ownership and management lines make sense to MISA and ZATCA.
For the tax incentives, ZATCA requires at least one director who is resident in the Kingdom, and board meetings where strategic decisions are taken must be held in Saudi Arabia. In practice the head is resident.
Then the RHQ breaches its licence conditions. The review tests the hiring plan before you apply.
0% income tax on eligible income from eligible RHQ activities for a renewable 30 years, under ZATCA’s RHQ tax rules. Income from other activities pays the normal 20%.
No, only eligible income from qualifying activities. Other income is taxed normally.
No. It pays 20% on the foreign share and zakat on any Saudi or GCC share.
ZATCA registration, annual returns and the annual economic substance report, plus a valid MISA licence and continued compliance with the RHQ conditions.
At 0% for dividends, payments to related persons and payments to unrelated persons for services the RHQ needs, as long as the payments relate to eligible activities.
Normal VAT rules apply. Charges to group entities count as supplies, and registration is mandatory once taxable supplies pass SAR 375,000 in 12 months.
From the date the RHQ licence is issued, and ZATCA’s rules describe the period as renewable.
Yes. After a 90-day correction notice and escalating fines, ZATCA can suspend them, in coordination with MISA, if a substance breach persists.
An RHQ licence takes as long as the group’s documents from several countries take to legalise. MISA’s own review is quick once the file is complete.
On the date the licence is issued: six months for mandatory activities, twelve for staff and optional activities.
At application. Pick only activities the RHQ will really carry out, because at least three must be running within a year.
Yes. MISA sets one fee for the whole registration period when it approves the licence, payable within 30 days of notification, or the registration is void.
Yes, after the MISA registration. See Commercial Registration.
An RHQ needs its own RHQ registration. We review your entities and recommend whether to restructure or add one.
Yes, or embassy legalisation, depending on each issuing country. See attestation and apostille.
At least 15 full-time staff on RHQ activities within a year of the licence.
At least three at executive director or vice-president level, with skills developed at the group headquarters or another regional HQ.
Yes, many do, on Saudi work visas and residency. See visas and Iqama.
Labour rules apply, and MISA describes facilitation for RHQs. We confirm current terms when planning hires. See GOSI and Qiwa.
Not for MISA’s licence condition, which asks for 15 full-time employees on RHQ activities. ZATCA’s substance test is separate and counts part-timers in proportion to their time.
Before the licence. Senior regional hires rarely close in under a few months.
Yes, once registered. See corporate bank accounts.
Yes, apart from limited exceptions. Since 1 January 2024 government entities do not contract with multinational groups lacking an RHQ in Saudi Arabia.
Yes. Contracts estimated at SAR 1 million or less are outside it, and a bid from a group without an RHQ can be accepted if it is the only technically compliant bid, or ranks among the best technically and is at least 25% cheaper than the next. The buyer requests the exemption on Etimad before the tender starts.
That depends on the tender and on whether one of the exceptions applies. We align the RHQ timeline with your bid pipeline.
No. It removes a barrier; contracts are still won on merit.
MISA’s temporary registration covers a foreign company delivering one government contract. Whether it helps depends on the RHQ rule’s exceptions.
Yes. Work back from the bid deadline: the licence itself is quick, but legalising documents from several countries can take weeks.
The tax and zakat return, the economic substance report to ZATCA, CR confirmation, MISA’s annual update, and GOSI and Qiwa records.
Through a MISA amendment, subject to the activities on its list.
Staff, tax and records are closed in order, then the MISA registration cancelled. The incentives end with the licence.
Yes. It files audited statements with its annual return, and its RHQ income has to be identifiable in them.
Only by restructuring and re-registering, so settle the form before applying.
Your team, or our PRO and compliance service, from a shared calendar.
References
Opened before quoting. Arab News is cited only because the Etimad exemption process has no public official page we could open. The tax incentives depend on the current rules; your tax advisers should confirm them.
Eligibility
We reply within one working day with a first view on eligibility and what a full review would cover.
Connected services
Foreign-owned LLC formationYour own Saudi company, owned from abroad.Read about Foreign-owned LLC →
Branch office registrationYour existing company, operating in Saudi Arabia.Read about Branch of a foreign company →
Investor visa and IqamaResidency for owners and general managers.Read about Investor visa & Iqama →
GOSI, Qiwa and Muqeem registrationEmployer set-up so you can hire.Read about GOSI, Qiwa & Muqeem →From our guides: how to get business from NEOM as a supplier